

In prior editions of Founder Insights, I’ve written about the AI infrastructure reset underway: the $7T Hardware Renaissance, the networking chokepoint, and why inference economics will define the next wave of AI scale. Each piece points to the same structural truth: in every technological gold rush, the infrastructure layer captures disproportionate value.
Today I want to go one layer deeper, to the physical layer of the AI stack that makes AI possible at scale.
The center of gravity in AI infrastructure is shifting. Training dominated the early years. Inference is what defines the next decade. It is expected to be a 10X larger market than training over the next five to seven years, driven by real-time agents and production AI running continuously across billions of endpoints.
And as inference scales, modern AI models are trained and served across hundreds of thousands of processors that must behave as a single computer, and the performance of that computer is now set as much by the network connecting the chips as by the chips themselves.
This is a physics problem, not a software one. And physics problems create infrastructure companies.
Copper has been used to connect racks in data centers for decades. At the data rates AI demands, electrical signals survive only about a meter and a half over copper — which confines processing resources to a tightly coupled domain of a single rack and a few hundred GPUs. When a hyperscaler roadmap calls for thousands of GPUs operating as one system, breaking that ceiling means replacing copper with photonics.
Optical connectivity, moving data at the speed of light, is the connective tissue of AI infrastructure. Optical moves data at scale, cuts latency, and controls power consumption in ways copper can’t. The market that follows is expected to be more than $100B over the next five to seven years. That puts optical connectivity in the same strategic tier as GPUs and AI accelerators themselves, not a component, but a critical layer.
Legacy vendors and point solutions have failed to address a complexity at the heart of the AI data center. There are two distinct but intertwined networking challenges:
Solve one without the other, and it breaks down at the inference scale. This is a category-defining company problem, well beyond the scope of any incremental supplier.
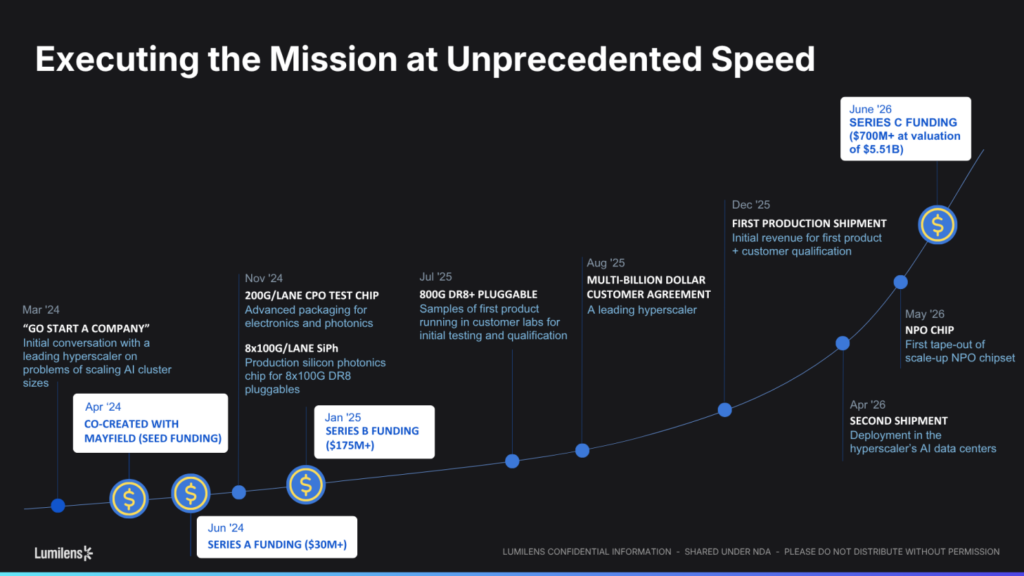
Lumilens is building the connectivity platform for AI infrastructure, and today the company is emerging from stealth — announcing more than $900+ million in total funding at a valuation of $5.5 billion. Lumilens designs and manufactures optical transceivers and NPO/CPO for scale-out and scale-up, respectively, and treats manufacturing as a product in its own right, from chip assembly to high-volume production.
What struck me most was the discipline behind the company’s founding. Lumilens was built around a question that most founders skip: Is this problem real, and will it still matter ten years from now? In early 2024, the team set out to solve connectivity problems that most of the largest AI clusters only foreshadowed — but problems a top hyperscaler was already encountering as it built out its roadmap.
18-months later, Lumilens’ scale-out product completed qualification and began shipping to that hyperscaler’s production data centers under a multi-billion-dollar agreement. They scaled in direct response to real customer demand. In Mayfield’s 56-year history, we’ve never seen execution and growth like this before.
The Lumilens portfolio spans the full connectivity stack of an AI data center:
Every product is built on LumiCoreTM, the company’s platform spanning silicon photonics, mixed-signal ICs, electrical-optical interposers, and optical systems — all built in-house. A single platform across the portfolio lets Lumilens move from design to customer-qualified product in months rather than years, and ensures each product is engineered for high-volume manufacturing from Day One.
Manufacturing is treated as a product in its own right, from photonic-chip assembly to high-volume production. That gives customers what the optics industry rarely has: fast innovation matched by the ability to scale production just as fast.
Scaling at this speed comes with real constraints running in parallel: supply chain pressure, design bandwidth, and a shortage of photonics talent that the industry largely let atrophy for a decade. Lumilens addresses all three head-on. The reason they can is people.
Founder and CEO Ankur Singla is building his fourth infrastructure company. Two of his prior companies, Contrail Systems and Volterra, were acquired by Juniper Networks and F5. He’s joined by a team that has been advancing optical interconnect technology well before AI turned it into a bottleneck. Founder-market fit here runs deep.
What also sets Lumilens apart is how the company operates internally. Ankur’s philosophy is radical transparency: share as much information as possible across the team, board, and investors to make better decisions faster. In a hardware company racing with hyperscaler timelines, that kind of collective intelligence is a competitive advantage.
The market structure here mirrors earlier Internet infrastructure moments in telecom: a small number of hyperscalers account for most of AI infrastructure purchasing. Winning a hyperscaler can define a company. The right approach, and the one Lumilens is taking, is to be the best possible partner to a lead customer while thoughtfully diversifying over time.
In the PC era, Intel and Microsoft captured the platform. In the Internet era, Cisco and Juniper powered the backbone. In the cloud era, Arista emerged. Each platform shift consolidates infrastructure first, then triggers an explosion of application innovation on top of it.
AI is following the same pattern, only faster and on a greater scale. The toll booths of the AI era are made of silicon, foundation models, and fiber. Optical connectivity is the fiber layer finally coming into its own.
Mayfield has been investing at the infrastructure layer for over 56 years, across more than 100 infrastructure exits. We have seen this movie before: infrastructure consolidates first, then the application innovation follows. The stack is still forming. The workflows are not yet reinvented. The companies that own the physical connectivity layer will collect the toll every time AI scales.
Our conviction here runs deeper than a single company. In the AI era, we believe value is created across the full stack, from semiconductors all the way up to agentic applications. Optical connectivity is foundational to everything built above it.
Lumilens was designed from Day One with that full-stack reality in mind: a clear business model, a go-to-market strategy, unit economics, and a long-term technology vision baked in from the start. That is what founder-market fit looks like at the infrastructure layer – and exactly what you would expect from a fourth-time entrepreneur who has seen every stage of company building.
We believe this layer will produce an industry-defining company.
Bottom line: Optical connectivity is the missing infrastructure layer that makes AI clusters economically and performance-viable at scale, and the window to define that category is right now.


